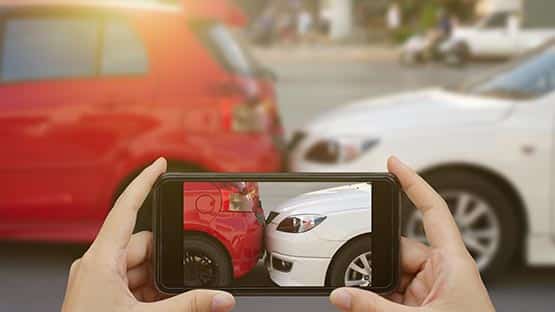
Most drivers figure the repair estimate starts at the body shop, with somebody walking around the car with a clipboard writing down what’s broken.
But on a growing share of claims, the number that ends up governing your repair and your payout gets written before your car ever sees a lift, from photos you snapped in a parking lot with your phone.
That first number carries more weight than most people realize. Knowing how it gets set is the difference between accepting an estimate and negotiating one.
The photos you take become the file
The claim now starts in the app. Insurers walk you through a short sequence of guided shots: corners of the vehicle, close-ups of the damage, the VIN, the odometer. It feels like a convenience feature when it’s actually the moment your evidence gets locked in.
GEICO’s version shows how tight the sequence is: its Easy Photo Estimate walks the policyholder through 10 photos and takes about 15 minutes to complete. State Farm, Chubb, Allstate, USAA, and most other large carriers run similar flows. If a panel is dented in a way the guided shot doesn’t capture, or if there’s a noise that only shows up when the car is driven, none of that reaches the file the estimator opens.
Whatever you don’t photograph, the adjuster doesn’t see. Whatever you do photograph, the adjuster sees first, before you have any number of your own to compare it to. If you were hurt in the crash and someone else’s carrier is asking you to submit these photos, talk to a car accident attorney before you upload anything, because those same photos will land in the injury file too.
AI writes the first number before a human looks
Once the photos land, they don’t sit in a queue waiting for a person. Computer vision models trained on millions of prior claims label the damaged parts, classify severity, and pull parts and labor pricing from the carrier’s rate tables. In many workflows, a draft estimate exists within minutes.
The scale here is not small. When a tool that widely deployed suggests a number, that tends to anchor everything downstream: the offer to you, the authorization sent to the shop, the reserve set on the file.
The offer lands in your inbox fast
Speed is the selling point. Payment can be issued in as little as one business day after the photos are reviewed, and some claims settle inside 48 hours. The messaging is friendly, the money is real, and the button to accept is right there.
A fast offer feels like good service, and often it is, for a bumper scuff or a cracked mirror housing. On anything more complicated, accepting quickly can foreclose options you didn’t know you had. Before you tap accept, know what a photo-based estimate tends to miss:
- Structural damage. Bent frame rails, cracked subframes, and misaligned unibody sections rarely show in an exterior photo.
- Suspension and steering. A hit that looks cosmetic can bend control arms or knock alignment out in ways only a rack will find.
- Sensors and calibration. Cameras, radar units, and parking sensors behind a bumper cover often need recalibration after replacement, and that labor is easy to leave off a first pass.
- Internal components. Radiators, condensers, airbag modules, and wiring harnesses can be damaged behind panels that photograph as intact.
Supplements are the real negotiation
The shop opens the car up and finds more. That’s the norm, not the exception. The additional damage gets written up as a supplement, sent back to the carrier, and then approved, questioned, or partially denied.
A consumer explainer from Experian lays out the accuracy debate plainly: insurers defend photo estimates as reasonable first passes, while body shops routinely report initial numbers that come in low and have to be reworked through supplements.
What to do before you tap accept
- Take more photos than the app asks for. Shoot every angle, every panel, the interior, the wheels, and anywhere fluids may have leaked. Keep the originals on your phone with their timestamps intact.
- Get an independent shop estimate. A written estimate from a body shop you chose, not one steered to you, gives you a real number to hold against the insurer’s.
- Don’t cash the check as a settlement. On some claims, endorsing the first payment can be treated as accepting it in full. Ask in writing whether the payment is partial or final before you deposit it.
- Ask for a re-inspection if hidden damage appears. Once the car is apart, request that the carrier send an appraiser in person or accept the shop’s supplement documentation.
- Keep injury and property claims separate in your head. Accepting a repair number doesn’t settle a bodily injury claim, but statements you make while handling the car damage can end up in the injury file.
The photo-based claim isn’t going away, and for most fender-benders it works fine. The trap is treating the first number as the number. It’s an opening offer, generated fast, from a limited view of the car.
This content is provided for informational purposes only and is not a substitute for professional advice. AFP editorial staff were not involved in the creation of this content.
 Share