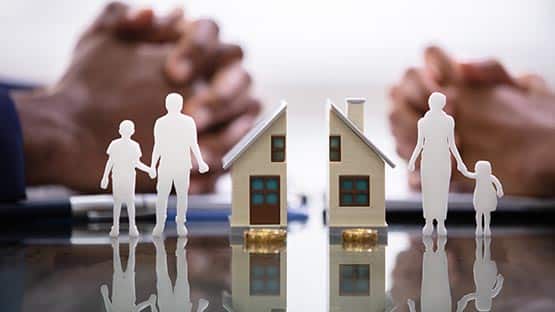
Divorce is often described in emotional terms, but it is also a significant financial reorganization. Decisions made in the early stages can affect housing, pensions, tax, investments and long-term security for years to come. Even couples who have broadly agreed that their relationship is over may discover that separating their finances is far more complicated than expected.
Taking stock before beginning formal proceedings can help both parties make informed decisions, avoid unnecessary conflict and identify problems that may otherwise emerge too late. It is not about treating a marriage like a business transaction. It is about understanding the practical consequences of ending a shared financial life.
Establish the full financial picture
The first step is to gather accurate information. Many couples have an incomplete understanding of their household finances, particularly where one person has managed the money, run a business or dealt with investments.
Create a clear record of:
- Bank and savings accounts
- Property, mortgages and other secured borrowing
- Pensions and investment portfolios
- Business interests, trusts and inherited assets
- Credit cards, personal loans and tax liabilities
- Insurance policies and valuable personal possessions
The aim is not simply to calculate what is in joint accounts. Financial disclosure may need to cover assets held individually, because ownership in one person’s name does not automatically determine how an asset will be treated during a divorce.
It is also important to obtain recent statements and supporting documents. A property valuation from several years ago, for example, may no longer reflect the current market. Likewise, pension values can fluctuate and business accounts may not tell the whole story about an owner’s financial position.
Understand the difference between value and liquidity
A couple may appear wealthy on paper while having relatively little cash available for immediate expenses. This distinction becomes particularly important when one household becomes two.
A family home may be the most valuable asset, but it cannot necessarily pay school fees, rent or legal costs without being sold or refinanced. A pension may represent substantial long-term value, but access is often restricted and may have tax implications. A private company may be worth a considerable amount, yet its value may depend on future performance and cannot always be easily realized.
Before agreeing that one person will keep a particular asset, consider:
- How much it is worth after tax, debt and transaction costs.
- Whether it produces income or requires ongoing expenditure.
- How easily it could be sold or converted into cash.
- Whether its value is likely to rise or fall.
- What financial needs each person will have in the short and long term.
This prevents a common mistake: comparing assets solely by their headline value rather than by their practical usefulness.
Consider the cost of living after separation
A household that was financially comfortable may become stretched once expenses are duplicated. There may be two rents or mortgages, separate utility bills, additional travel between homes and new childcare arrangements. Inflation and higher borrowing costs can make this transition more difficult than anticipated.
Both parties should prepare realistic post-separation budgets. These should distinguish between essential and discretionary spending and include irregular costs such as car repairs, school trips, insurance renewals and home maintenance. A budget based only on current direct debits is unlikely to provide a reliable picture.
If children are involved, financial planning should also account for their changing needs. Childcare, education, extracurricular activities and healthcare can all affect the affordability of proposed arrangements. The parent with whom children spend less time may still face substantial costs, particularly if suitable accommodation is required.
Where substantial wealth, overseas assets, trusts or business interests are involved, early advice from specialist divorce lawyers for complex cases can help clarify what information is needed and which issues may require expert valuation. The earlier these questions are identified, the less likely it is that negotiations will be delayed by missing or disputed evidence.
Do not overlook pensions
Pensions are frequently one of the largest assets in a marriage, yet they are often treated as an afterthought. Their value may not be obvious from annual statements, and different pension arrangements can be difficult to compare.
A defined contribution pension may have a stated fund value, while a defined benefit scheme promises an income based on salary and service. These figures are not interchangeable. A pension valuation may therefore need to be interpreted by a specialist rather than accepted at face value.
Possible solutions can include sharing a pension, offsetting its value against other assets or making alternative arrangements for retirement. The right approach depends on the parties’ ages, health, earning capacity, housing needs and expected retirement income. A person who gives up a claim to a pension in exchange for retaining the family home may later find that they have valuable property but insufficient income.
Independent financial advice can be useful alongside legal advice, particularly when assessing tax, investment risk and future retirement needs.
Review tax and borrowing consequences
Financial decisions made during divorce may trigger tax liabilities or affect access to borrowing. Selling or transferring property, disposing of investments and restructuring business ownership can all have consequences. Tax rules also change, so advice based on an old transaction or a friend’s experience may be unreliable.
Credit should be reviewed as well. Check joint loans, overdrafts, guarantees and credit cards. Closing a joint account does not necessarily remove responsibility for borrowing already incurred. Nor should one party assume that an informal promise to make future payments will protect them from a lender.
If a mortgage is involved, speak to the lender early. A person may want to retain the family home but be unable to pass affordability checks alone. Understanding the borrowing position can prevent unrealistic proposals and reveal whether sale, refinancing or a different housing arrangement is necessary.
Protect finances without escalating conflict
It is sensible to protect personal finances, but actions taken in haste can create legal and practical difficulties. Moving money, cancelling insurance, running up debt or disposing of assets without agreement may damage trust and invite further scrutiny.
Instead, keep records, preserve important documents and maintain reasonable access to funds for ordinary living expenses. Change passwords for personal accounts and secure confidential information, while avoiding attempts to access accounts that are not yours. If there is a genuine concern about hidden assets, coercive control or financial abuse, seek advice promptly rather than trying to investigate recklessly.
Plan for the next stage
The strongest financial decisions are usually based on reliable information and a realistic view of life after divorce. Before formal negotiations begin, consider what housing, income, childcare and retirement security will look like for each person. Identify which issues are agreed, which require evidence and which may need specialist input.
Legal advice is not only for couples expecting a courtroom dispute. It can also help people understand their options, document an agreement properly and avoid settling issues that have not been fully assessed. Financial advisers, pension specialists, accountants and valuers may also have an important role.
Divorce cannot remove every uncertainty, but preparation can reduce avoidable surprises. By understanding the complete financial picture, testing proposals against real-world costs and taking advice where matters are complex, couples can approach separation with greater clarity and a better chance of reaching arrangements that remain workable long after the paperwork is complete.
This content is provided for informational purposes only and is not a substitute for professional advice. AFP editorial staff were not involved in the creation of this content.
 Share